Two Bills You Thought Were Unrelated Are Actually the Same Bill
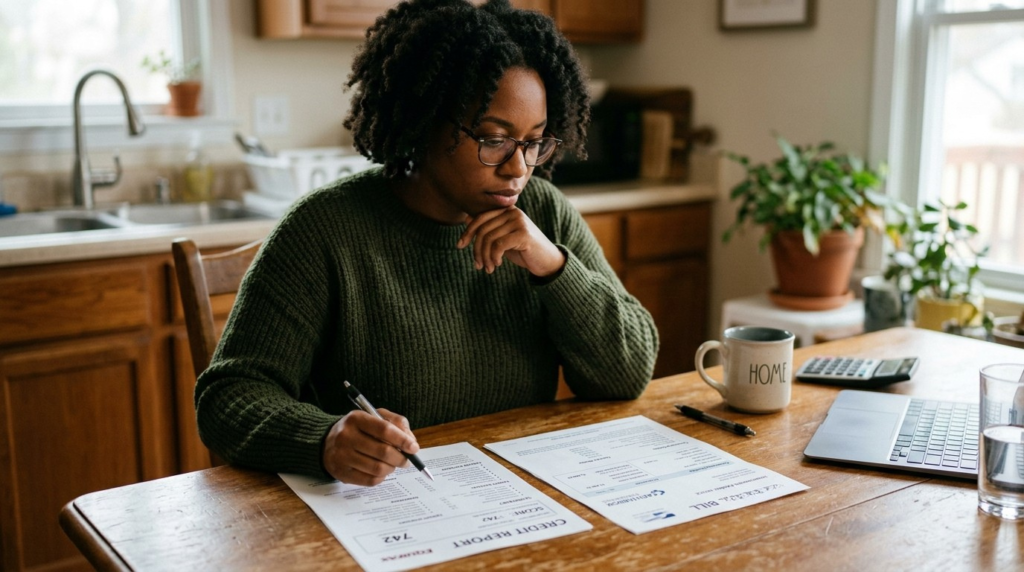
Most Floridians have no idea their credit report is quietly setting their auto and home insurance premiums — sometimes by 40-100%. Here’s how that works, and how fixing one number improves both.
A lot of people assume their insurance premium is based purely on their driving record, their home’s age, and their location. In Florida, there’s a third factor working quietly in the background: your credit-based insurance score — a specialized score, separate from your regular credit score, that most insurers in Florida are legally allowed to use when setting your rate.
The gap this creates is significant. Drivers with poor credit in Florida pay 40-100% more for the exact same coverage as drivers with excellent credit — meaning two neighbors with identical driving records and identical cars can pay dramatically different premiums, based entirely on what’s sitting on their credit report.
Find an Insurance Professional →
What a Credit-Based Insurance Score Actually Is
It’s a separate statistical score — not identical to your regular financial credit score — designed to predict how likely you are to file an insurance claim, based on patterns in your credit history. Insurers argue that people who manage their finances responsibly also tend to file fewer claims, and use this as a legitimate rating factor alongside your driving record, home age, and location. Whether or not that logic feels fair, it’s currently legal in Florida and used by a majority of auto and homeowners insurers in the state.
Good News: Florida Rates Are Actually Dropping in 2026
Here’s a piece of genuinely good news buried in the numbers: Florida’s top auto insurers are projecting an average 8% rate decrease for 2026, following legislative reforms that improved the state’s loss ratios dramatically. That means even drivers with average credit may see some relief this year — but the credit factor still determines exactly how much of that relief actually reaches you.
How to Improve Both Numbers at the Same Time
- Pay every bill on time, even small ones — payment history is the single biggest factor in both traditional and insurance credit scoring.
- Pay down revolving credit card balances — lower utilization improves both scores simultaneously.
- Don’t close old credit accounts — length of credit history matters for both.
- Shop your insurance annually regardless of credit — rates for identical coverage can vary 40-50% between insurers in Florida.
- Bundle home and auto policies — often a 10-25% discount independent of credit.
Why This Deserves More Attention in Our Community
Credit-based insurance scoring quietly compounds existing financial pressure: someone already managing tighter credit, perhaps recovering from identity theft or working through medical debt, ends up paying more for the exact same insurance coverage as someone with a cleaner credit history — even with an identical driving and claims record. Understanding this connection is the first step toward addressing it deliberately, rather than accepting a high premium as unavoidable.
🧮 Free Tool: Credit Tier Premium Impact Estimator
A general illustration based on published industry ranges — actual impact varies by insurer. Not a quote.
Frequently Asked Questions
Does my credit score really affect my insurance premium in Florida?
Yes. Florida allows insurers to use a credit-based insurance score, separate from your standard credit score, as a rating factor for auto and homeowners insurance.
How much can credit affect my insurance rate?
Drivers with poor credit in Florida can pay 40-100% more than those with excellent credit for identical coverage.
Are Florida auto insurance rates dropping in 2026?
Yes, Florida’s top auto insurers are projecting an average 8% rate decrease for 2026 following legislative reforms, though individual results vary by credit and other factors.
What’s the fastest way to improve a credit-based insurance score?
Paying bills on time and reducing credit card balances are the most impactful actions, since payment history and credit utilization affect both standard and insurance-based scoring.
Where can I find a Black-owned insurance professional in Florida?
BlackOwnedFlorida.com maintains a directory of Black-owned insurance agents across Florida.
Browse the Directory →